1. Introduction
Traditional banking regulation, embodied in the first two Basel Accords, was microprudential. It assumed that if each institution holds enough capital against its own risks, the system as a whole will be safe. The collapse of Lehman Brothers in September 2008 and the near-failure of AIG exposed the flaw in this logic. Losses spread well beyond the institutions directly hit by the subprime shock. They travelled through counterparty exposures, forced asset sales, the drying-up of wholesale funding, and a general loss of confidence. Systemic risk, meaning the risk that the failure or distress of one or more institutions impairs the functioning of the financial system and causes significant harm to the real economy, came to be understood as a property of the system rather than of its parts.
Network science offers a natural language for this idea. When banks are represented as nodes and their financial relationships as weighted, directed edges, one can ask questions that balance-sheet analysis of single institutions cannot answer. Which institutions are “too interconnected to fail”? Does greater interconnectedness make the system more resilient by spreading risk, or more fragile by creating channels for contagion? How large must an initial shock be to cause a cascade of defaults? Haldane and May (2011) drew explicit analogies with ecological and epidemiological networks, and since then a large literature has developed at the intersection of economics, finance, physics, and applied mathematics.
This paper has three aims. First, it presents the main classes of network models of banking contagion in a common notation so that their assumptions and mechanisms can be compared directly. Second, it synthesises the theoretical and empirical findings on how network structure affects systemic stability. Third, it discusses practical issues that stand between these models and their use in supervision, notably data limitations, network reconstruction, and the choice between exposure-based and market-based measures, and draws policy implications.
The remainder of the paper is organised as follows. Section 2 sets out the network representation of a banking system. Section 3 reviews models of direct contagion. Section 4 covers indirect contagion through fire sales and funding. Section 5 introduces multilayer networks. Section 6 discusses the relationship between topology and stability. Section 7 presents a stylised numerical illustration. Section 8 addresses data and reconstruction. Section 9 reviews market-based connectedness measures. Section 10 discusses policy implications, Section 11 outlines limitations and directions for future research, and Section 12 concludes.
2. The Banking System as a Network
Consider a system of
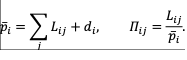
The book equity of bank
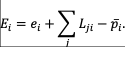
This simple structure already allows standard network statistics to be computed. These include in-degree and out-degree (the number of creditors and debtors), strength (total weighted exposure), density, clustering, assortativity, and centrality measures such as eigenvector centrality, PageRank, and betweenness. Empirical studies of interbank markets consistently find several regularities. The networks are sparse. Their degree distributions are heavy-tailed. They are disassortative, meaning large banks tend to trade with small banks. They are well described by a core–periphery structure in which a small, densely connected core of large banks intermediates between a large periphery of smaller institutions (Boss et al., 2004; Soramäki et al., 2007; Craig and von Peter, 2014; in ’t Veld and van Lelyveld, 2014).
Descriptive statistics are informative, but they are not a model of risk. A bank with high betweenness centrality is not necessarily dangerous, and a peripheral bank can be the trigger of a cascade if its creditors are thinly capitalised. For this reason the literature has moved from topology alone to explicit models of how losses propagate, which we now review.
3. Direct Contagion: Counterparty Default Cascades
3.1 The Eisenberg–Noe clearing model
The foundational model of direct contagion is that of Eisenberg and Noe (2001). It asks what payments banks can actually make when some cannot meet their obligations in full. Under limited liability and absolute priority of debt over equity, and with all creditors of a defaulting bank paid pro rata, a clearing payment vector p* satisfies
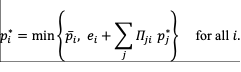
Each bank pays either what it owes or everything it has, whichever is smaller. Eisenberg and Noe show that a clearing vector always exists, that it is unique under mild regularity conditions, and that it can be computed with a “fictitious default” algorithm. Starting from full payment, banks that cannot pay are identified, payments are recalculated, and the procedure is repeated until no new defaults occur. The sequence of rounds naturally distinguishes fundamental defaults, caused by the shock itself, from contagious defaults, caused by losses on claims against other defaulted banks.
A key and often overlooked property of the model is loss conservation. With no deadweight costs of default, the total loss to creditors and shareholders across the system equals the initial loss on external assets. The network redistributes losses but does not amplify them. Glasserman and Young (2015) build on this observation to derive general bounds on how much contagion can amplify losses. They show that for realistic balance sheets, contagion through the Eisenberg–Noe mechanism alone is modest. Substantial amplification requires additional channels such as bankruptcy costs, fire sales, or confidence effects.
3.2 Default costs
Rogers and Veraart (2013) extend the model by assuming that a defaulting bank recovers only a fraction α∈[0,1] of its external assets and a fraction β∈[0,1] of its interbank receivables:
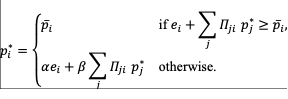
When
3.3 Threshold models and the probability of contagion
A second tradition, adapted from models of epidemics and cascades on random graphs, abstracts from exact payment flows and asks when default spreads through a network. In the model of Gai and Kapadia (2010), each bank holds interbank assets spread across its counterparties, and a counterparty default imposes a loss on its creditors (with zero recovery in the baseline). A bank is “vulnerable” if the default of a single counterparty is enough to wipe out its capital. For a bank with k debtors and evenly spread interbank assets AiIB, vulnerability occurs when

Using generating-function techniques for random directed graphs, Gai and Kapadia derive the conditions under which a single initial default causes a system-wide cascade. They find that the probability of contagion is non-monotonic in average connectivity. At low connectivity, the network is fragmented and shocks cannot travel far. At high connectivity, each exposure is small and banks are well diversified. Between these extremes lies a “window” of connectivity in which contagion is rare but, when it occurs, reaches most of the system. This is the formal counterpart of the “robust-yet-fragile” characterisation of financial networks. Gai, Haldane and Kapadia (2011) extend the approach to funding liquidity contagion and show that greater complexity and concentration of interbank links increase fragility.
3.4. DebtRank and distress propagation
Default-based models share a limitation. A creditor bank suffers a loss only when its debtor actually defaults, whereas in reality a deterioration in a counterparty’s solvency reduces the market value of claims on it well before any default. DebtRank, introduced by Battiston et al. (2012) and reformulated by Bardoscia et al. (2015), captures this by propagating distress rather than default. Let hit∈0,1 be the relative equity loss of bank i at step t, and let Wij denote the exposure of bank i to bank j relative to i’s initial equity. The dynamics in the linear version are
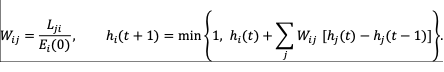
Each bank passes on its incremental distress to its creditors in proportion to their exposures. The systemic impact of an initial shock is measured as the additional equity loss it induces across the system, weighted by the economic value 
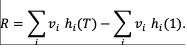
Using this approach, Battiston et al. (2012) analysed the network of emergency loans provided by the Federal Reserve during the crisis and found that a relatively small group of institutions was systemically central at the peak of the crisis. The method has since been widely used in supervisory applications. Its main advantages are computational simplicity and sensitivity to distress below the default threshold. Its main limitation is that the linear transmission of losses, which assumes that a percentage loss of equity maps one-for-one into a loss of claim value, can overstate contagion. Later work links the valuation of interbank claims more carefully to default probabilities (Bardoscia et al., 2019).
4. Indirect Contagion: Fire Sales and Funding Liquidity
4.1 Overlapping portfolios and fire sales
Direct counterparty exposures are only one channel of contagion, and empirically often not the most important. When banks hold common assets, a bank that suffers a loss and sells assets to restore its leverage or meet regulatory ratios depresses the prices of those assets. This causes mark-to-market losses at every other bank holding them, even if the two banks have no bilateral relationship at all. The relevant network is then a bipartite graph linking banks to asset classes.
Cifuentes, Ferrucci and Shin (2005) showed that the interaction between capital requirements, mark-to-market accounting, and endogenous asset prices can produce contagion even in systems where direct exposures are too small to cause cascades. Greenwood, Landier and Thesmar (2015) proposed a tractable framework in which banks target a constant leverage ratio. Let M be the matrix of portfolio weights of banks across assets, B a diagonal matrix of leverage, A the diagonal matrix of bank assets, and
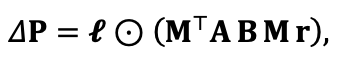
where ⊙ denotes element-wise multiplication. This yields measures of each bank’s “systemicness,” meaning the losses its deleveraging imposes on others, and “indirect vulnerability,” meaning the losses it suffers from others’ deleveraging. Caccioli et al. (2014) study cascades on overlapping-portfolio networks and find the same kind of non-monotonic relationship between diversification and stability as in direct-exposure models. Individual diversification reduces the risk for each bank but increases portfolio overlap and thus the potential for system-wide fire sales.
4.2 Funding liquidity contagion
Liquidity contagion runs in the opposite direction to solvency contagion. When a bank faces losses or uncertainty, it may hoard liquidity by withdrawing short-term interbank lending. Its borrowers then lose funding and may be forced into fire sales or default even though they are solvent. Allen and Gale (2000) showed in a seminal paper that the propagation of liquidity shocks depends on the structure of the interbank market. A complete network in which each bank holds claims on all others is more resilient than an incomplete, ring-shaped network, because the losses from a shock are spread more widely. Gai, Haldane and Kapadia (2011) model liquidity hoarding as a response to counterparty distress and show how it can freeze an entire interbank market, as occurred in August 2007 and after September 2008.
5. Multilayer Networks
Banks are connected simultaneously through many types of relationships: unsecured interbank loans, repurchase agreements, derivatives, securities cross-holdings, payment flows, and common asset holdings. Each relationship type forms a layer of a multilayer (or multiplex) network, and the layers are not independent. A loss in one layer, such as a derivatives exposure, can trigger margin calls in another layer and fire sales in a third.
Using Mexican supervisory data covering several exposure types, Poledna et al. (2015) show that estimating systemic risk from any single layer considerably underestimates the total systemic risk of the system, and that the systemic risk of the combined network is not the simple sum of the risks of the individual layers. Montagna and Kok (2016) develop a multilayer model of the European banking system that combines long-term exposures, short-term funding, and common exposures, and find that interactions between the layers produce significant non-linear amplification. These results carry an important methodological lesson. A supervisor that examines only one type of exposure, typically bilateral large exposures, is likely to reach overly reassuring conclusions.
6. Network Topology and Stability
A central question of the literature is whether interconnectedness makes the system safer or more fragile. The answer depends on the size of the shock, the contagion mechanism, and the structure of the network.
The “robust-yet-fragile” property. As Section 3.3 showed, highly connected networks absorb most shocks well but become vulnerable to system-wide failure when a sufficiently large shock hits a critical point. Haldane (2009) used this idea to describe the pre-crisis financial system. Dense connections created an illusion of safety through diversification while making the system as a whole susceptible to a sudden collapse.
Phase transitions. Acemoglu, Ozdaglar and Tahbaz-Salehi (2015) provide a rigorous treatment in an Eisenberg–Noe-type framework. When shocks are small, a more diversified pattern of interbank obligations enhances stability, and the complete network is the most stable structure. When shocks exceed a critical threshold, the same interconnections act as a propagation mechanism. The complete network then becomes among the most fragile structures, and weakly connected networks, in which subsets of banks are only loosely linked, perform better. The relationship between connectivity and stability therefore undergoes a phase transition.
Integration and diversification. Elliott, Golub and Jackson (2014) distinguish between integration, meaning how much each organisation depends on others, and diversification, meaning how many counterparties it has. Both have non-monotonic effects on the extent of cascades. Cascades are largest at intermediate levels of diversification and grow with integration. This helps explain why the empirical relationship between simple connectivity measures and crisis outcomes is often weak.
Core–periphery structure. In a core–periphery network, contagion within the core can be rapid, and the core acts as a bridge through which shocks travel from one part of the periphery to another. At the same time, the core banks are typically large, well capitalised, and closely supervised. The location of the initial shock and the capitalisation of core banks relative to their exposures therefore matter greatly. The main message is that no single topological statistic, whether density, degree, or centrality, is a sufficient indicator of systemic risk. Topology must be combined with balance-sheet data and an explicit model of loss propagation.
7. A Stylised Numerical Illustration
To make the preceding mechanisms concrete, consider a system of three banks, A, B, and C, with the following obligations. A owes 12 to B, B owes 10 to C, and C owes 4 to A. The external assets are eA=9, eB=0, and eC=10. For simplicity, there are no external liabilities, and each bank’s equity equals its assets minus its interbank obligations. Scenario 1 applies a shock of 4 to A’s external assets under the Eisenberg–Noe rules; Scenario 2 applies the same shock with Rogers–Veraart default costs α=β=0.8. Table 1 summarises the outcomes.
Table 1.
Payments and equity of banks in the three-bank example
|
Bank |
Baseline equity |
EN: payment |
EN: equity |
RV: payment |
RV: equity |
|
A |
1 |
9 of 12 (default) |
0 |
7.2 of 12 (default) |
0 |
|
B |
2 |
9 of 10 (contagious default) |
0 |
5.76 of 10 (contagious default) |
0 |
|
C |
16 |
4 of 4 |
15 |
4 of 4 |
11.76 |
|
System |
19 |
|
15 |
|
11.76 |
Note: EN = Eisenberg–Noe (no default costs); RV = Rogers–Veraart (α=β=0.8). Shock of 4 applied to A’s external assets in both scenarios.
Baseline. All banks can pay in full. Bank A has 9+4=13≥12, B has 0+12=12≥10, and C has 10+10=20≥4. Equities are EA=1, EB=2, and EC=16, and total system equity is 19.
Shock without default costs (Eisenberg–Noe). An adverse shock of 4 reduces A’s external assets to eA=5. Bank A now has 5+4=9<12 and defaults, paying p*A=9. B then receives only 9 and has 9<10, so it defaults despite not being hit by the shock directly and pays p*B=9. C receives 9 instead of 10 but remains solvent, pays its 4 in full, and its equity falls to 15. The clearing vector is p*=9,9,4. Total system equity falls from 19 to 15, a loss of exactly 4, which equals the initial shock. The network redistributes the loss among the three banks but does not amplify it.
Shock with default costs (Rogers–Veraart). Bank A defaults and pays 0.8×5+0.8×4=7.2. Bank B receives 7.2, defaults, and pays 0.8×0+0.8×7.2=5.76. Bank C receives 5.76 and remains solvent with equity of 10+5.76-4=11.76. Total system equity falls from 19 to 11.76, a loss of 7.24. The amplification ratio, defined as the system-wide loss divided by the initial shock, is 7.24/4≈1.81.
This small example illustrates three general points. First, contagious defaults can occur at banks whose own assets are untouched by the shock. Second, in the absence of deadweight costs, direct contagion is a zero-sum redistribution of losses, consistent with Glasserman and Young (2015). Third, even moderate default costs can almost double the systemic impact of a shock. The practical size of default costs, including legal costs, delays in recovery, and the discount on assets sold in distress, is therefore one of the most important parameters in any network stress test.
8. Data Limitations and Network Reconstruction
The usefulness of network models depends on the quality of exposure data. In many jurisdictions, supervisors observe only exposures above a large-exposure reporting threshold, or only each bank’s total interbank assets and liabilities rather than the full matrix of bilateral positions. Researchers outside supervisory authorities usually face even greater limitations. Estimating the full network from partial data is therefore a practical necessity.
The traditional approach is maximum-entropy reconstruction (Upper and Worms, 2004), which spreads each bank’s interbank assets and liabilities as evenly as possible across counterparties subject to the observed row and column totals. However, this produces an almost complete network, whereas real interbank networks are sparse. Using complete Italian data, Mistrulli (2011) shows that maximum entropy can underestimate the extent of contagion in some scenarios and overestimate it in others, because it replaces a few large concentrated exposures with many small ones. Alternative methods include the minimum-density approach, which constructs the sparsest network consistent with the marginal totals (Anand et al., 2015), and fitness-based or configuration models from statistical physics, which use each bank’s size to estimate the probability that a link exists and then assign weights (Cimini et al., 2015). A comparative “horse race” of reconstruction methods across several national datasets (Anand et al., 2018) found that no single method dominates across all criteria. Methods that reproduce the density and degree distribution of the true network perform better in estimating systemic risk than those that only reproduce the marginal totals. Squartini et al. (2018) provide a comprehensive survey.
For supervisors, the practical lesson is twofold. First, investing in the collection of granular bilateral exposure data, including derivatives from trade repositories and securities holdings, yields significant returns. Second, when reconstruction is unavoidable, results should be reported as ranges across several methods rather than as point estimates.
9. Market-Based Measures of Connectedness
An alternative to exposure-based models infers connectedness from the co-movement of market prices, such as equity returns and credit default swap (CDS) spreads. These measures do not require confidential balance-sheet data and can be updated at high frequency.
Diebold and Yilmaz (2014) construct connectedness networks from the generalised forecast-error variance decomposition of a vector autoregression. The weight of the edge from j to i is the share of the forecast-error variance of i attributable to shocks in j. Aggregating these weights produces measures of total system connectedness and of each institution’s net contribution to the system (“to” minus “from”). Billio et al. (2012) use pairwise Granger causality tests and principal components analysis on the returns of banks, broker-dealers, insurers, and hedge funds, and find that the financial sector became markedly more interconnected in the years before the crisis. These network measures complement well-known tail-risk indicators that are not explicitly network-based, including CoVaR (Adrian and Brunnermeier, 2016), marginal expected shortfall and systemic expected shortfall (Acharya et al., 2017), and SRISK (Brownlees and Engle, 2017).
Market-based measures have clear advantages: they are timely, forward-looking, and reflect all channels of interdependence, including those not captured in supervisory reports. They also have important limitations. Correlation in prices does not identify the mechanism of transmission and may reflect common exposure to macroeconomic factors rather than contagion. The measures tend to rise during crises rather than before them, which limits their value as early-warning indicators. They are also unavailable for unlisted banks, which make up most of the banking system in many countries. Exposure-based and market-based approaches should therefore be treated as complements. The former explain how contagion would occur, and the latter indicate whether markets perceive the system as fragile.
10. Implications for Macroprudential Policy
Identifying systemically important institutions. The Basel Committee’s methodology for global systemically important banks (G-SIBs) includes interconnectedness, measured by intra-financial-system assets and liabilities and securities outstanding, as one of five categories of indicators. Network models provide a richer basis for this assessment. Rankings based on DebtRank or on contribution to cascades in stress simulations capture a bank’s position in the network and the fragility of its counterparties, not merely the volume of its interbank business. A bank with moderate exposures to many thinly capitalised counterparties may be more systemically important than a larger bank with exposures to well-capitalised ones.
Calibrating capital surcharges. If a bank’s failure imposes an externality on the rest of the system, efficient regulation should make it internalise this externality. Network models make it possible to link capital surcharges to a bank’s systemic impact rather than to its size alone. Proposals of this kind include a systemic risk tax on individual transactions proportional to their contribution to DebtRank (Poledna and Thurner, 2016). This would give banks an incentive to restructure their exposures toward a less fragile network.
System-wide stress testing. Traditional supervisory stress tests apply a macroeconomic scenario to each bank separately and do not account for second-round effects. The findings reviewed in this paper suggest that stress tests should incorporate at least three additional elements. First, they should include direct contagion with realistic default costs. Second, they should model fire sales driven by common asset holdings and regulatory constraints. Third, they should include funding liquidity dynamics. Several central banks and the European Central Bank have developed frameworks along these lines, and the “top-down” macroprudential stress tests they produce have become an important complement to bank-level exercises.
Market infrastructure. The mandatory central clearing of standardised over-the-counter derivatives introduced after the crisis fundamentally reshaped derivatives networks. Many bilateral exposures were replaced by exposures to central counterparties (CCPs). This reduces counterparty risk and makes the network more transparent, but it also concentrates risk in a small number of nodes. The CCPs themselves become critical hubs whose resilience, default waterfalls, and margin procyclicality require close supervision.
Resolution. The Rogers–Veraart result that default costs drive amplification provides a direct argument for effective resolution regimes. Tools that allow a failing bank to be resolved quickly, with continuity of critical functions and limited losses of value, such as bail-in and bridge banks, raise the effective recovery rates α and β in the model’s terms. They therefore reduce systemic amplification, not just the loss to the failing bank’s own creditors.
11. Limitations and Directions for Future Research
Several limitations of the current literature deserve attention. First, most models are static or mechanical. They take the network as given and treat banks as passive transmitters of losses. In reality, banks adjust their exposures in response to perceived risk, and the network changes endogenously, often most sharply during a crisis. Models that combine strategic network formation with contagion dynamics are still at an early stage.
Second, the growth of non-bank financial intermediation, including investment funds, money-market funds, and insurers, means that banking-sector networks capture a shrinking share of the relevant system. The episodes of market stress in March 2020 and the 2023 failures of several US regional banks illustrate the role of deposit runs, interest-rate exposures, and interactions with non-banks.
Third, climate-related financial risk has created a new area of application. Battiston et al. (2017) show how exposures to climate-policy-relevant sectors can be propagated through financial networks, but the interaction between physical and transition risk and network contagion remains underexplored.
Fourth, machine-learning methods, particularly graph neural networks, offer new tools for predicting bank distress from network data. Their use in supervision will require careful attention to interpretability and to the risk of overfitting on the small number of crisis observations available.
Finally, the empirical validation of contagion models remains difficult. Systemic crises are rare, counterfactuals are unobservable, and model outputs are highly sensitive to parameters, such as recovery rates and price impact, that are poorly identified in normal times.
12. Conclusion
The network approach has changed how economists and supervisors think about systemic risk in banking. It shows that the stability of the system is not the sum of the stability of its parts, and that the same connections that diversify risk in normal times can spread it in a crisis.
The main conclusions of this review can be summarised as follows. The relationship between interconnectedness and stability is non-monotonic and depends on the size of the shock. Direct counterparty contagion alone is usually modest, and significant amplification comes from default costs, fire sales, funding runs, and the interaction of multiple network layers. Network analysis requires granular data, and where this data is unavailable, reconstruction methods must be used with caution. Exposure-based and market-based measures offer complementary perspectives.
For macroprudential policy, network models provide tools for identifying systemically important institutions, calibrating capital requirements to systemic externalities, and designing stress tests that account for second-round effects. Integrating these tools into routine supervision, while recognising their limitations, remains one of the most important tasks for financial stability authorities.
Список литературы
- Acemoglu, D., Ozdaglar, A., & Tahbaz-Salehi, A. (2015). Systemic risk and stability in financial networks. American Economic Review, 105(2), 564–608
- Acharya, V. V., Pedersen, L. H., Philippon, T., & Richardson, M. (2017). Measuring systemic risk. Review of Financial Studies, 30(1), 2–47
- Adrian, T., & Brunnermeier, M. K. (2016). CoVaR. American Economic Review, 106(7), 1705–1741
- Allen, F., & Gale, D. (2000). Financial contagion. Journal of Political Economy, 108(1), 1–33
- Anand, K., Craig, B., & von Peter, G. (2015). Filling in the blanks: Network structure and interbank contagion. Quantitative Finance, 15(4), 625–636
- Anand, K., et al. (2018). The missing links: A global study on uncovering financial network structures from partial data. Journal of Financial Stability, 35, 107–119
- Bardoscia, M., Battiston, S., Caccioli, F., & Caldarelli, G. (2015). DebtRank: A microscopic foundation for shock propagation. PLoS ONE, 10(6), e0130406
- Bardoscia, M., Barucca, P., Codd, A. B., & Hill, J. (2019). Forward-looking solvency contagion. Journal of Economic Dynamics and Control, 108, 103755
- Battiston, S., Puliga, M., Kaushik, R., Tasca, P., & Caldarelli, G. (2012). DebtRank: Too central to fail? Financial networks, the FED and systemic risk. Scientific Reports, 2, 541
- Battiston, S., Mandel, A., Monasterolo, I., Schütze, F., & Visentin, G. (2017). A climate stress-test of the financial system. Nature Climate Change, 7, 283–288
- Billio, M., Getmansky, M., Lo, A. W., & Pelizzon, L. (2012). Econometric measures of connectedness and systemic risk in the finance and insurance sectors. Journal of Financial Economics, 104(3), 535–559
- Boss, M., Elsinger, H., Summer, M., & Thurner, S. (2004). Network topology of the interbank market. Quantitative Finance, 4(6), 677–684
- Brownlees, C., & Engle, R. F. (2017). SRISK: A conditional capital shortfall measure of systemic risk. Review of Financial Studies, 30(1), 48–79
- Caccioli, F., Shrestha, M., Moore, C., & Farmer, J. D. (2014). Stability analysis of financial contagion due to overlapping portfolios. Journal of Banking & Finance, 46, 233–245
- Cifuentes, R., Ferrucci, G., & Shin, H. S. (2005). Liquidity risk and contagion. Journal of the European Economic Association, 3(2–3), 556–566
- Cimini, G., Squartini, T., Garlaschelli, D., & Gabrielli, A. (2015). Systemic risk analysis on reconstructed economic and financial networks. Scientific Reports, 5, 15758
- Craig, B., & von Peter, G. (2014). Interbank tiering and money center banks. Journal of Financial Intermediation, 23(3), 322–347
- Diebold, F. X., & Yilmaz, K. (2014). On the network topology of variance decompositions: Measuring the connectedness of financial firms. Journal of Econometrics, 182(1), 119–134
- Eisenberg, L., & Noe, T. H. (2001). Systemic risk in financial systems. Management Science, 47(2), 236–249
- Elliott, M., Golub, B., & Jackson, M. O. (2014). Financial networks and contagion. American Economic Review, 104(10), 3115–3153
- Gai, P., & Kapadia, S. (2010). Contagion in financial networks. Proceedings of the Royal Society A, 466(2120), 2401–2423
- Gai, P., Haldane, A., & Kapadia, S. (2011). Complexity, concentration and contagion. Journal of Monetary Economics, 58(5), 453–470
- Glasserman, P., & Young, H. P. (2015). How likely is contagion in financial networks? Journal of Banking & Finance, 50, 383–399
- Glasserman, P., & Young, H. P. (2016). Contagion in financial networks. Journal of Economic Literature, 54(3), 779–831
- Greenwood, R., Landier, A., & Thesmar, D. (2015). Vulnerable banks. Journal of Financial Economics, 115(3), 471–485
- Haldane, A. G. (2009). Rethinking the financial network. Speech delivered at the Financial Student Association, Amsterdam. Bank of England
- Haldane, A. G., & May, R. M. (2011). Systemic risk in banking ecosystems. Nature, 469, 351–355
- in ’t Veld, D., & van Lelyveld, I. (2014). Finding the core: Network structure in interbank markets. Journal of Banking & Finance, 49, 27–40
- Mistrulli, P. E. (2011). Assessing financial contagion in the interbank market: Maximum entropy versus observed interbank lending patterns. Journal of Banking & Finance, 35(5), 1114–1127
- Montagna, M., & Kok, C. (2016). Multi-layered interbank model for assessing systemic risk (ECB Working Paper No. 1944). European Central Bank
- Poledna, S., Molina-Borboa, J. L., Martínez-Jaramillo, S., van der Leij, M., & Thurner, S. (2015). The multi-layer network nature of systemic risk and its implications for the costs of financial crises. Journal of Financial Stability, 20, 70–81
- Poledna, S., & Thurner, S. (2016). Elimination of systemic risk in financial networks by means of a systemic risk transaction tax. Quantitative Finance, 16(10), 1599–1613
- Rogers, L. C. G., & Veraart, L. A. M. (2013). Failure and rescue in an interbank network. Management Science, 59(4), 882–898
- Soramäki, K., Bech, M. L., Arnold, J., Glass, R. J., & Beyeler, W. E. (2007). The topology of interbank payment flows. Physica A, 379(1), 317–333
- Squartini, T., Caldarelli, G., Cimini, G., Gabrielli, A., & Garlaschelli, D. (2018). Reconstruction methods for networks: The case of economic and financial systems. Physics Reports, 757, 1–47
- Upper, C., & Worms, A. (2004). Estimating bilateral exposures in the German interbank market: Is there a danger of contagion? European Economic Review, 48(4), 827–849